
In This Update: Investment Spotlight | Stock Market Review | Economic Review & Outlook
Chart of the Month | Closing Statements
INVESTMENT SPOTLIGHT
The Trillion-Dollar AI Buildout
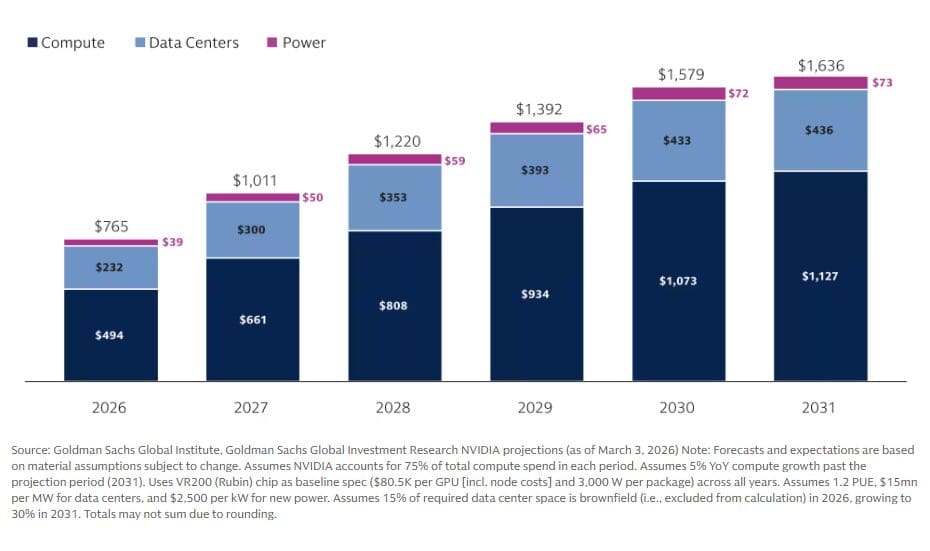
Artificial intelligence yet again remained a dominant investment story in August, but the narrative has evolved from simply discussing technological potential to understanding the enormous infrastructure required to make that potential a reality. Industry estimates now suggest roughly $2.5 trillion of AI-related capital expenditures could be deployed over the next three years, making this one of the largest investment cycles in modern history.
Evidence of this spending boom was on display throughout the month. South Korean Chip maker SK Hynix announced plans to invest more than $38 billion in new memory chip production facilities, while Broadcom unveiled plans to raise between $70 billion and $80 billion to finance infrastructure supporting the rapidly expanding AI ecosystem. Nvidia further reinforced confidence in the theme after reporting triple-digit growth in its AI-related businesses and issuing robust long-term revenue guidance. At the same time, emerging “neocloud” providers such as Nebius and CoreWeave are experiencing explosive growth as companies seek specialized computing resources for AI applications. While the scale of spending has raised questions about future returns, demand for AI infrastructure continues to suggest that businesses are still in the early stages of adoption.
MARKET INDEX RETURNS | August 2026 | YTD 2026 |
S&P 500 Index | 2.7% | 13.1% |
Russell 2000 Index | 1.0% | 20.2% |
MSCI EAFE Index | 2.0% | 13.8% |
Bloomberg US Agg. Bond Index | 0.4% | -0.3% |
FTSE 3 Mo. T-Bill Index | 0.3% | 2.5% |
Anticipated AI investments through 2028 is roughly equivalent to the entire annual economic output of Canada.
STOCK MARKET REVIEW & OUTLOOK
New Highs Signal Broadening Market Strength
The stock market delivered another impressive month as both the Dow Jones Industrial Average and the S&P 500 reached new all-time highs after spending much of July under pressure. Technology stocks played a major role in the rebound, with investors taking advantage of the prior month’s weakness and rotating back into several of the market’s leading growth companies.
Corporate earnings provided substantial support for the rally. With almost the entire S&P 500 having reported second-quarter results, earnings growth is tracking at approximately 52% year-over-year, more than double analyst expectations. Technology and software companies were particularly strong performers, with firms such as Nvidia, Salesforce, and CrowdStrike delivering results that highlighted continued demand for AI-related products and services.
Looking ahead, investors will likely focus on whether earnings momentum can continue while interest rates remain elevated. Seasonal trends also warrant attention, as September has historically been the weakest month of the year for equity markets. Nevertheless, continued earnings strength, improving investor sentiment, and broad participation across sectors suggest the market’s foundation remains constructive despite the likelihood of periodic volatility.
S&P 500 SECTOR RETURNS | August 2026 | YTD 2026 |
Communication Services | -1.2% | 0.1% |
Consumer Discretionary | -0.1% | 0.0% |
Consumer Staples | -0.7% | 9.5% |
Energy | 7.0% | 44.2% |
Financials | 1.3% | 6.2% |
Healthcare | 4.9% | 11.1% |
Industrials | -2.5% | 13.5% |
Information Technology | 6.2% | 22.9% |
Materials | 6.0% | 16.7% |
Utilities | -4.8% | 0.3% |
Real Estate | -1.9% | 13.1% |
ECONOMIC REVIEW & OUTLOOK
Growth Holds Firm While Inflation Remains a Challenge
Economic data offered a mixed but generally encouraging picture. Second-quarter GDP growth was confirmed at a modest 1.5% annualized pace, but upward revisions to consumer spending reinforced the view that households remain a key driver of economic activity. Restaurant spending continued to rise during the month, although overall retail sales declined due to softer online purchases, auto sales, and lower gasoline expenditures.
The labor market showed signs of cooling as nonfarm payrolls unexpectedly declined by 23,000 jobs, with weakness concentrated in government employment, retail, leisure, and hospitality. While the unemployment rate fell to 4.1%, much of the improvement resulted from lower labor force participation rather than stronger hiring activity. At the same time, inflation data delivered mixed signals. Consumer and producer inflation readings improved during the month, helping reduce expectations for an immediate rate hike. However, the Fed’s preferred inflation measure, Personal Consumption Expenditures (PCE), remained well above the central bank’s target, and Federal Reserve Chair Kevin Warsh reinforced a hawkish stance at Jackson Hole, emphasizing that inflation has yet to show meaningful underlying improvement.
Housing remained a challenge for many Americans. Existing home sales declined again as elevated mortgage rates and limited inventory weighed on activity. Conditions remain particularly difficult in the Northeast, where constrained supply continues to push home prices higher despite affordability concerns. The changing composition of the housing market highlights these pressures, with million-dollar homes now representing a significantly larger share of transactions than they did a decade ago.
CHART OF THE MONTH
AI Capital Expenditures Expected to Be Over $1 Trillion per Year Going Forward
Source: Goldman Sachs Global Institute
CLOSING STATEMENT
Looking Ahead
August’s market performance illustrated that strong fundamentals can coexist with meaningful uncertainty. Investors continue to navigate a complex environment characterized by slowing job growth, persistent inflation, elevated interest rates, and significant technological disruption. Yet despite these challenges, corporations are delivering strong earnings, consumers continue to spend, and businesses are investing aggressively in the technologies that may shape the next decade of economic growth.
As we enter September, investors will closely monitor labor market conditions, inflation trends, Federal Reserve communications, and the sustainability of the AI investment cycle. While seasonal market weakness and the possibility of additional monetary tightening could create periods of volatility, strong earnings growth and continued corporate investment provide reasons for optimism. The market’s recent ability to reach new highs despite slowing job growth and elevated interest rates highlights the importance of looking beyond headline risks. The coming months may ultimately reveal whether today’s record levels are being supported by temporary enthusiasm or by the early stages of another meaningful cycle of innovation and productivity growth.
Please reach out to one of your Account Officers or any member of our Executive Leadership Team to discuss topics raised in this letter or if we can assist you in any other way.
Meet The Plimoth Investment Advisors Executive Leadership Team
Steven A. Russo, CFA
Chairman of the Board
508‑591‑6202
srusso@pliadv.com
Mark J. Gendreau, CFP ®
President & CEO
508-591-6211
mgendreau@pliadv.com
Edward J. Misiolek
Senior Vice President & Operations Officer
508‑675‑4316
emisiolek@pliadv.com
Teresa A. Prue, CFP®
Senior Vice President &
Head of Fiduciary Services and Administration
508‑591‑6221
tprue@pliadv.com
