
In This Update: Investment Spotlight | Stock Market Review | Economic Review & Outlook
Chart of the Month | Closing Statements
INVESTMENT SPOTLIGHT
Looking Beneath the Surface
September’s relatively quiet headline performance masked significant differences beneath the surface. The Consumer Discretionary sector offered one of the clearest examples: on September 9th, 10 of the sector’s 47 S&P 500 constituents reached 52-week lows, while not a single company reached a new high. Combined with weakness in the Dow, the divergence highlights how broad market indexes can sometimes obscure meaningful deterioration among individual stocks and sectors.
At the same time, the artificial intelligence investment theme continued to demonstrate strength, although enthusiasm has become more selective. Oracle reported robust cloud demand and a sizable backlog tied to AI infrastructure, while Adobe delivered solid AI-related growth metrics. Investor reactions were mixed, however, as questions surrounding valuations and the enormous capital expenditures required to support AI growth remained front and center. As the market becomes more discerning, earnings growth and the ability to generate returns from these investments may play a larger role in separating winners from losers in the months and years to come.
MARKET INDEX RETURNS | September 2026 | YTD 2026 |
S&P 500 Index | -0.3% | 12.7% |
Russell 2000 Index | -5.3% | 13.9% |
MSCI EAFE Index | -3.0% | 10.3% |
Bloomberg US Agg. Bond Index | -2.6% | -2.9% |
FTSE 3 Mo. T-Bill Index | 0.3% | 2.9% |
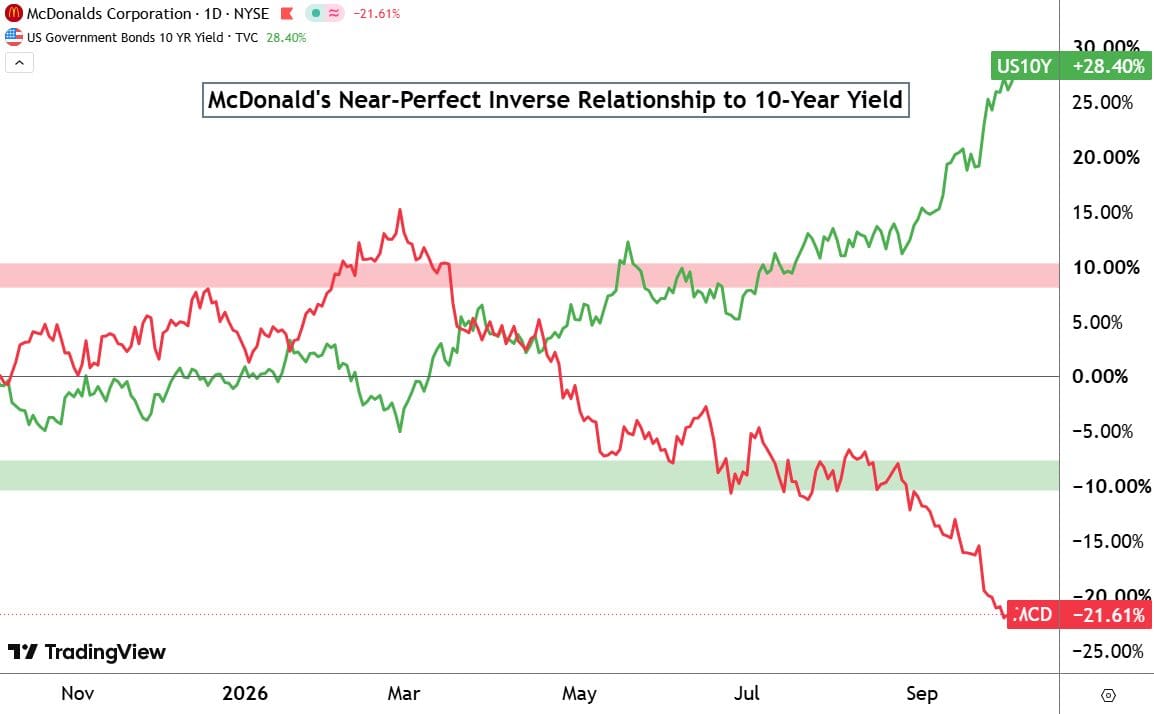
Higher yields have reduced the relative appeal of dividend stocks, weighing on their performance.
STOCK MARKET REVIEW & OUTLOOK
A Market of Contrasts
One source of support remains corporate profitability. With the second-quarter earnings season nearly complete, S&P 500 earnings growth is tracking near 52%, marking the strongest pace since the post-pandemic recovery in 2021. Still, September demonstrated that strong earnings alone may not be enough to lift the entire market as Treasury yields rise and financial conditions tighten. Heading into the fourth quarter, continued strength in technology and corporate earnings provides a constructive backdrop, however elevated rates and growing weakness in economically sensitive areas suggest market leadership could remain increasingly selective.
S&P 500 SECTOR RETURNS | September 2026 | YTD 2026 |
Communication Services | 4.3% | 4.5% |
Consumer Discretionary | -5.8% | -5.8% |
Consumer Staples | -3.3% | 6.0% |
Energy | -2.7% | 40.3% |
Financials | -7.2% | -1.4% |
Healthcare | -0.9% | 10.2% |
Industrials | -4.4% | 8.5% |
Information Technology | 4.5% | 28.4% |
Materials | -6.7% | 8.8% |
Utilities | -5.9% | -5.7% |
Real Estate | -6.1% | 5.3% |
ECONOMIC REVIEW & OUTLOOK
Resilience Faces a Higher-Rate Test
The economic picture remained mixed during September. August retail sales increased a stronger-than-expected 1.2%, signaling consumers continue to spend despite higher borrowing costs. That strength, however, has become increasingly concentrated, with the top 10% of households now accounting for nearly half of U.S. consumer spending. Meanwhile, September’s labor report showed signs of cooling as payroll growth disappointed, unemployment rose to 4.2%, and wage growth continued to moderate.
Inflation and interest rates remain the primary challenges. August PCE inflation came in at 3.4% headline and 3.0% core, both above the Federal Reserve’s 2% target despite coming in better than analyst expectations. The Fed raised rates by 25 basis points in September to a 3.75%-4.00% target range and maintained a hawkish tone, leaving open the possibility of additional tightening. Meanwhile, oil prices climbed above $100 per barrel during the month amid escalating U.S.-Iran tensions, adding to existing inflationary pressures. However, prices moderated into month-end, closing just shy of $90 per barrel. Treasury yields surged in September as investors adjusted to the prospect that inflation and interest rates could remain elevated for longer, adding another headwind for consumers, businesses, and financial markets.
CHART OF THE MONTH
Rising Yields Impacting Dividend Aristocrats
Source: Goldman Sachs Global Institute
CLOSING STATEMENT
Looking Ahead
September’s market performance reflected a growing divide between areas of strength and weakness. Technology shares continued to benefit from enthusiasm surrounding AI and strong underlying earnings, while more economically sensitive areas struggled under the weight of rising rates and increasingly selective consumer spending. With the S&P 500 largely unchanged and the Dow declining sharply, the month served as a reminder that a strong year for equities does not necessarily translate into steady gains across every sector or index.
As we enter the fourth quarter, Treasury yields may prove to be one of the most important variables for markets. Higher rates are increasing the cost of capital, challenging equity valuations, and gradually tightening financial conditions, even as corporate earnings and consumer spending remain resilient. The question heading into year-end is whether those fundamental strengths can continue to offset the pressure from higher borrowing costs. September did not provide a definitive answer, but the growing divergence across markets suggests that balance will be increasingly important in the months ahead.
Please reach out to one of your Account Officers or any member of our Executive Leadership Team to discuss topics raised in this letter or if we can assist you in any other way.
Meet The Plimoth Investment Advisors Executive Leadership Team
Steven A. Russo, CFA
Chairman of the Board
508‑591‑6202
srusso@pliadv.com
Mark J. Gendreau, CFP ®
President & CEO
508-591-6211
mgendreau@pliadv.com
Edward J. Misiolek
Senior Vice President & Operations Officer
508‑675‑4316
emisiolek@pliadv.com
Teresa A. Prue, CFP®
Senior Vice President &
Head of Fiduciary Services and Administration
508‑591‑6221
tprue@pliadv.com
